


US Real Estate Investment for Foreign Investors: What to Check Before You Buy
Last updated: September 2026
Short answer: Yes, foreigners can invest in US real estate. There is no federal law requiring US citizenship or residency to buy property here. What actually changes for a foreign investor is everything around the purchase: financing terms, tax treatment on rental income, a 15% withholding requirement (FIRPTA) when you sell, and US estate tax exposure that can be far higher than what applies to US citizens. None of this makes the investment a bad idea. It just means you need to do the homework before you fall in love with a listing, not after.
Most foreign investors get this backwards. They find a city they like, browse listings, and pick a property before they know whether the market, the numbers, or the tax rules actually support it. Then the tax bill or the FIRPTA withholding notice shows up at closing, and it is too late to change course. Investors who do well start somewhere else. They look at the market, the numbers, and the ownership structure first. The property comes last.
On this page:
US Real Estate Investment for Foreign Investors: Where the Market Stands
Direct answer: Foreign buying has slowed from earlier highs, both in dollar terms and in the number of homes bought. That makes careful evaluation more important right now, not less.
According to the National Association of Realtors' 2026 International Transactions report, foreign buyers purchased $45.3 billion worth of existing US homes, about 67,100 properties, between April 2025 and March 2026. That is a 19.1% drop in dollar value and a 14% drop in the number of sales from the year before. It is the second-lowest total NAR has recorded since it started tracking this data in 2009. High prices, tight inventory, and higher borrowing costs outweighed a weaker dollar that would normally make US property cheaper for foreign buyers.
Who is buying, and where:
Rank | Country | Share of foreign purchases | Notable detail |
1 | Canada | 16% | Led by number of purchases |
2 | Mexico | 14% | Close behind Canada |
3 | China | (see note) | Highest dollar total at $7.6B; average purchase price near $1 million |
4 | India | 9% | $3.7B in total purchases |
Florida stayed the top destination state, followed by California and Texas.
None of this means the opportunity is gone. It means the buyers who are still active tend to be more careful. They run real numbers instead of chasing momentum, and that is the standard this guide is built around.
Step 1: Check the Market Before You Check the Property
Direct answer: A listing photo tells you nothing about whether a market makes sense. Before you compare properties, ask five questions about the market itself.
Is demand real or is it just a spike? Job growth and population growth support rents for years. A short-term price jump driven by outside money usually does not.
What is being built right now? A wave of new construction can push down both rents and resale values in a market that looked tight two years ago.
How does the state treat landlords versus tenants? This affects how long an eviction takes, whether you can raise rents, and how much control you actually have as an owner.
Is the local economy spread across industries? A market held up by one big employer carries more risk than a market with many different industries.
How does the state tax owners who do not live there? Some states keep this simple. Others add extra rules you will not find out about until your first tax filing.
This is also where "best states for foreign real estate investment" stops being a vague question. Florida and Texas, for example, have no state income tax, which makes things simpler for a foreign investor collecting rent, and both are consistently among the top states for international buyers. States with more rules or higher transfer taxes are not automatically a bad choice. They just need a more careful return calculation before you commit money.
Step 2: Match the Property Type to Your Actual Goal
Direct answer: "What is the best property to buy?" cannot be answered until you know what you actually want from it: cash flow, growth in value, or spreading out your money across different assets.
Property type | Typically suits | Watch out for |
Single family rental | Steady cash flow, long-term growth, easier to manage from abroad | Landlord-tenant rules vary a lot by state |
Small multifamily (2 to 4 units) | Higher cash flow, cost savings from scale | Non-resident buyers usually need a bigger down payment |
Condominium | Lower entry price, simpler upkeep | HOA fees and rules; some buildings do not allow short-term rentals at all |
Commercial or mixed use | Longer leases, possibly higher returns | Usually needs more complex financing and legal setup from the start |
Vacation or short-term rental | Income plus your own use of the property | Local short-term rental rules change often and can differ block to block |
Land or development | Long-term growth in value | Permitting and construction financing add complexity; rarely a good first US purchase |

Decide on your goal first. The type of property should follow from that, not the other way around.
Step 3: Build a Real Return Model, Not Just a Price Comparison

Direct answer: The asking price is the least useful number on the listing. What actually tells you if this is a good deal is your net return after all the costs that come with being a foreign, non-resident buyer.
Closing costs. These often run higher for foreign buyers because of extra legal, escrow, and compliance steps.
Realistic rent, not listing-site averages. Pull actual comparable rents in the area. Numbers on aggregator websites tend to run high.
Running costs. Property tax, insurance (much higher in coastal or high-risk states), HOA dues, money set aside for maintenance, and property management fees, which are close to a must if you are not physically in the US.
Financing terms. Non-resident buyers usually face down payments of 25% to 40%, higher interest rates, and fewer lenders willing to work with them compared to a US resident buyer.
Net yield after tax and fees. The number that actually matters, and the one no listing site shows you.
Exit plan. What a future sale looks like once you account for FIRPTA withholding and capital gains tax.
Run these numbers before you fall in love with a property, not after. This is also where local market research pays for itself, by pulling real comparable sales and cost data for your target market instead of relying on national averages that do not reflect what you will actually pay.
Step 4: Understand the Tax Rules
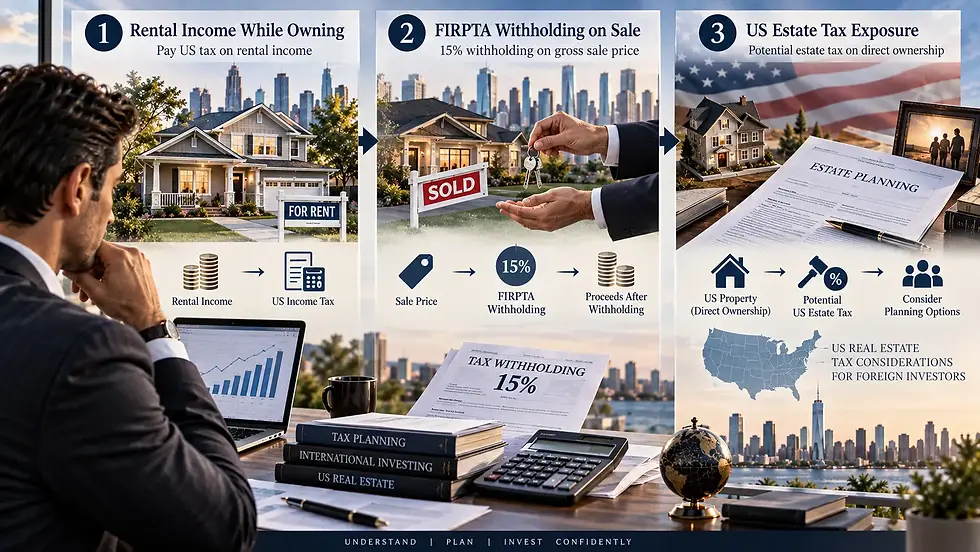
Direct answer: Three tax rules matter most for a foreign owner: a 30% withholding tax on your gross rental income while you own the property (you can often lower this with an election), a 15% FIRPTA withholding on the full sale price when you sell, and US estate tax that can start applying after just $60,000 if you own the property in your own name.
While you own the property
Rental income is taxed at a flat 30% on the gross amount you receive, unless you file an election under IRC Section 871(d) to be taxed on your net income (after expenses) instead. That election usually works out much better once you count mortgage interest, depreciation, and running costs, and it is one of the most commonly missed steps by foreign owners managing property without proper US tax help. Our international compliance and tax filing team walks clients through this decision before the first tenant moves in.
You will also generally need to file a US non-resident tax return, Form 1040-NR, every year you hold the property, even in a year you lose money.
When you sell: FIRPTA
The Foreign Investment in Real Property Tax Act is the single rule every foreign investor needs to understand before they buy, not after. Under FIRPTA, the buyer must withhold 15% of the full sale price, not your profit, and send it to the IRS at closing. Full details are on the IRS FIRPTA withholding page.
Say you sell a property for $800,000 that you bought for $700,000. The standard withholding is based on the full $800,000, not your $100,000 gain. Two things help with this:
Withholding is not your final tax bill. If your real tax owed is lower than what was withheld, you can file a return and get the difference back, though this can take several months.
Form 8288-B lets you apply ahead of time for a lower withholding amount that better matches what you will actually owe, instead of overpaying and waiting for a refund. File it too close to closing and it will not be processed in time, so plan ahead instead of leaving it to the last minute.
Estate tax: the risk most investors do not see coming
Foreign owners who hold US property directly, without a US company or other structure, can be hit with US estate tax after just $60,000, compared with several million dollars for US citizens and residents. That is a big gap, and it is the main reason many foreign investors choose not to hold property in their own name.
Step 5: Choose an Ownership Structure on Purpose
Direct answer: There is no single right structure for everyone. The right one depends on your goals, your home country's tax treaty with the US, and whether you care most about protecting yourself from liability, lowering your tax bill, or planning around estate tax.
Direct ownership. Simplest to set up, but no liability protection and full estate tax exposure.
US LLC. The most common middle-ground option, giving you liability protection with manageable paperwork. How it is taxed depends on the elections you make and how your home country treats US LLCs, which varies more than most people expect. Our foreign-owned LLC tax and reporting guide covers what actually needs to be filed each year, including Form 5472.
US C Corporation. Can lower estate tax exposure, since shares in a properly set-up holding company may fall outside US estate tax rules, but it adds corporate tax and withholding on any money paid out. Usually a better fit for long-term holds than for buying and selling often.
Layered structures, such as a foreign holding company that owns a US LLC, are used by more experienced investors to combine liability protection, tax treaty benefits, and estate planning. These need to be set up carefully to avoid creating extra US tax problems.
If you are setting up the company that will hold the property, our USA LLC and Corporation formation service handles the setup and pairs it with tax planning, so the structure you choose actually fits your investment plan instead of a one-size-fits-all template.
Step 6: Plan for Financing, Currency, and Other Logistics
Direct answer: Beyond the property itself, four things routinely catch first-time foreign buyers off guard: limited lender options, currency risk, rules around moving money across borders, and the near-necessity of hiring someone to manage the property for you.
Financing access. Not every US lender works with foreign, non-resident buyers, and the ones that do usually want a bigger down payment and take longer to approve a loan. Many first-time foreign buyers pay in cash to skip this hassle, then look into financing later once they have a US track record.
Currency risk. Both your purchase and your ongoing rental income are affected by changes between your home currency and the US dollar for as long as you own the property.
Moving the money. Wiring a large amount of money internationally comes with reporting requirements on both ends, and big transfers take time to clear. If you are moving money from India specifically, our guide on cross-border investment management for Indian founders covers LRS limits and RBI reporting that directly affect how, and how fast, you can fund a US purchase.
Managing the property from abroad. If you are not physically in the US, a reliable property manager is not optional. Build their fee into your numbers from the start, not as an afterthought once the first repair call comes in.
Local rules can change. Short-term rental rules, HOA restrictions, and zoning vary by city and can change over time. What is allowed in a building today is not guaranteed for the next three years.
Opening a US bank account as a non-resident is its own challenge worth solving early. Our US business banking support is built for founders and investors who do not have a US Social Security Number.
Investment Checklist

Before you put money down, you should be able to check every box below.
I have compared at least two or three target markets on fundamentals and tax rules, not just price.
The property type matches my actual goal: cash flow, growth in value, or spreading out my money.
I have worked out my net return after realistic costs, non-resident financing costs, and management fees.
I know whether the Section 871(d) net income election makes sense for my rental income.
I have a plan for FIRPTA withholding at sale, including whether Form 8288-B is worth filing.
I understand my US estate tax exposure and whether a different structure would lower it.
I have picked an ownership structure based on my specific situation, not a generic default.
Financing is confirmed, or I am planning to buy in cash.
I have accounted for currency risk over how long I plan to hold the property.
I have a reliable plan for managing the property from abroad.
I have checked the current local rules for how I plan to use the property.
I know what a future sale looks like after tax, not just what the property might grow to be worth.
If several boxes are still unchecked, that is not a reason to give up on the idea. It is a sign that the research and planning should happen before you make an offer, not after.
Frequently Asked Questions
Can foreigners invest in US real estate? Yes. There is no federal rule stopping foreigners from owning US real estate, and no requirement to be a citizen or resident. A few states stop certain foreign entities from buying farmland or property near specific infrastructure, but regular residential and commercial purchases are open to international buyers.
How can foreigners invest in US real estate? Most buy either directly in their own name or, more often for investment property, through a US LLC or another entity chosen for liability, tax, and estate planning reasons. The closing process follows the standard US steps, though foreign buyers usually need extra paperwork and, if financing, have fewer lenders to choose from.
Is US real estate a good investment for foreign investors? It can be, but that depends on the market, the property, and the structure, not on the asset type alone. Foreign buying has slowed from earlier highs, which makes careful evaluation more important than ever, not less.
Which US states are best for foreign real estate investors? Florida, Texas, and California are consistently the top states for international buyers, partly because Florida and Texas have no state income tax, and both have strong rental demand in their major cities. The right answer for you depends more on your budget, goal, and risk tolerance than on any general ranking.
What should foreign investors consider before buying US property? Market fundamentals, whether the property type matches your goal, a full cost and net return analysis, how rental income is taxed, FIRPTA at sale, US estate tax exposure, ownership structure, financing access, currency risk, and a realistic plan for managing the property from abroad.
What taxes should foreign investors consider when investing in US real estate? Three matter most: a 30% withholding tax on gross rental income, which you can often lower with an election; FIRPTA withholding of generally 15% of the full sale price when you sell; and US estate tax, which kicks in at a much lower amount for non-resident owners than for US citizens and residents, and often shapes which ownership structure makes sense.
Can foreigners buy investment property in the USA? Yes, with no citizenship or residency requirement. The real things to plan for are financing (terms differ a lot from what a US resident would get), how rental income and an eventual sale are taxed, and choosing an ownership structure that fits the size of the investment.
Where This Usually Goes Wrong, and How to Get It Right
Every step above connects to the next. The ownership structure you pick shapes your tax bill. Your tax bill shapes your real net return. Your net return decides whether the market and property type that looked good on paper actually deliver what you expected. Skip one step, and the number you end up with rarely matches the number you started with.
That is the gap Internation Corpus exists to close for international investors: market and investment research, tax planning and compliance, company formation, and cross-border banking support, all handled before your money moves, not cleaned up after a surprise FIRPTA bill or an estate tax problem you did not see coming.
If you are at the stage of comparing markets, working out your numbers, or figuring out how to structure a US real estate investment as a foreign national, that is exactly the conversation to have before you make an offer. Get a free consultation or request a quote and we will walk through what your specific situation actually needs.
This article is for general informational purposes and does not replace tax, legal, or investment advice. FIRPTA withholding rates, estate tax exemption amounts, and rental income elections can change. Confirm current numbers with a qualified tax professional or directly with the IRS before acting on them.


Comments